Engine version and the fill contract
Pin the simulator and identify when an intention can become a simulated transaction.
The engine is part of experiment identity
A source rule can be unchanged while a library upgrade changes warmup, order priority, fees or finalisation. Record engine version, data format, order semantics, cost policy and environment beside the rule. The teaching packet pins Backtesting.py 0.6.6 and records the actual numerical dependencies. It uses one-unit long market intentions, next-open fills, fixed fees and no forced final liquidation. Those choices define this software fixture; they are not a universal execution model for stocks, futures, crypto or options. A current library manual describes mechanisms, not the actual liquidity that a real broker would provide.
Keep decision and fill clocks distinct
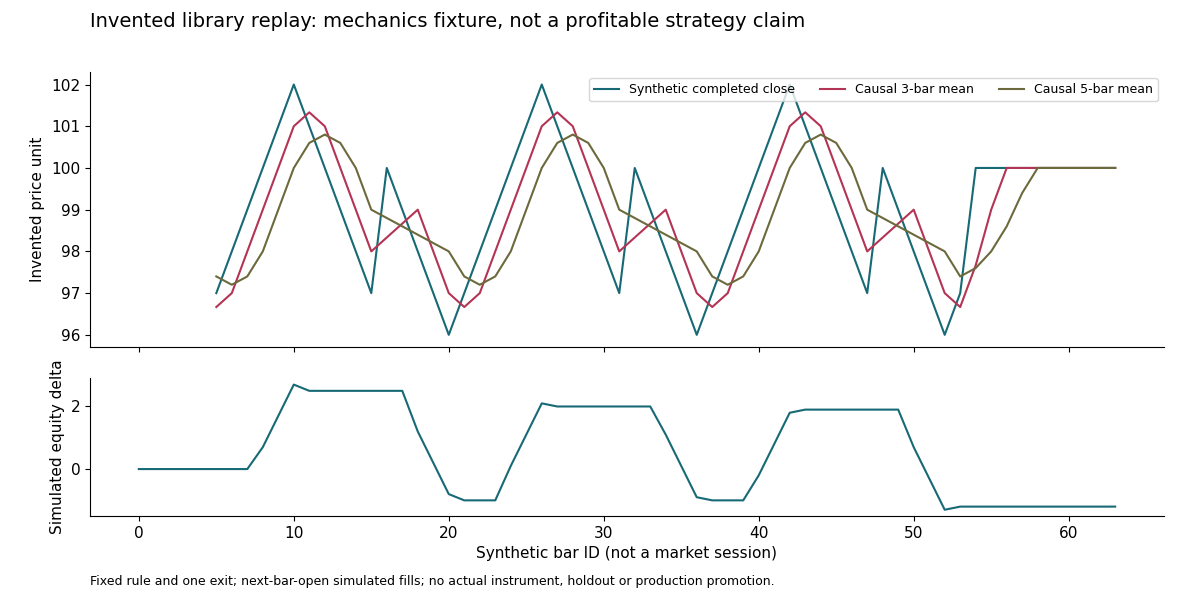
An intention based on a completed close cannot generally fill earlier inside that same unfinished bar without another order and information contract. In the example, intent bar 7 produces simulated entry at bar 8 open. The entry-fill bar is counted as completed holding bar one, so bar 10 close requests a whole exit and bar 11 open provides the simulated fill. Retain all four IDs, not just one transaction time. The arbitrary UTC labels in the input are invented and do not encode an exchange session, auction deadline or actual subscriber receiving event.
Fees and termination affect the result
A fixed 0.10 fee is assessed on each entry and each exit, giving 0.20 for a complete one-unit position. There is no separate spread, financing or slippage amount. Automatic final liquidation is disabled. Entry eligibility ends at bar 49, while buffer bars allow outstanding time exits to complete, so the fixture finishes flat rather than using an undeclared closing price. These are explicit constraints of the sample. A real economic study may need another contract, but changing it after viewing results creates a new experiment rather than another reconstruction of the original.
A fill policy is not financial assurance
The exported trade rows can be checked against synthetic open prices and independent cash arithmetic. That verifies the chosen model behaviour, not actual execution or a profitable hypothesis. The tutorial's next-open convention does not replace canonical VR observation-window fills or native minute exits. A real instrument task must preserve the authorised method, identities and master checks. No queue, partial fill, nonlinear payoff or broker recovery is represented by this small library fixture. The useful conclusion is a reproducible timing contract with named limitations, not a claim that every intended transaction would be achievable in a market.
Filled invented system case
The fictional rule emits intent 7, enters at synthetic open 8 at 99.2, requests its time exit at close 10 and exits at open 11 at 101.9. One-unit gross cash change is 2.7; two fixed fees total 0.20, leaving 2.50 in this simulated position. Five other positions remain in the same packet, including losers. Total net cash is negative 1.20. No real order or target probability is supplied.
| Object | Record | Bounded finding |
|---|---|---|
| Intent | Bar 7 completed close | No earlier fill |
| Entry | Bar 8 open; 99.2 | Library simulation |
| Exit request | Bar 10 completed close | One fixed rule |
| Exit fill | Bar 11 open; 101.9 | 2.50 net after declared fees |
Primary references and scope
Expanded source review: 13 October 2026. Documentation supports the stated mechanism, not a tested account, hypothetical fill or provider outcome.