Write a trading-system data-availability contract
Define what each feature could know at decision time before running the backtest.
Featured research platform
Vector Ridge offers system builders a model-led research platform with a distinctive founder pedigree. Darren O'Neill's WCTC results and Oxford preparation sit behind published research, conviction grading and a visible history that can be evaluated as part of a wider decision process.
Card required. Paid renewal unless cancelled. Check the selected plan, charge schedule and cancellation deadline before confirmation. Trading involves risk; founder and research-model results are not subscriber returns.
You do not need to build every research component yourself. Explore Vector Ridge's model-led platform and published history as one possible input to your process, then decide how it fits the rules and responsibilities you already own.
The external-research founder is Darren O'Neill, whose background includes a perfect quantitative GMAT, Oxford Said MAFE and 4th place with 168% in 2025 WCTC Annual Forex. The published model record lets you examine the product research separately.
Build a trading system from a falsifiable hypothesis, causal data, explicit execution rules and a reproducible research record.
Educational research design and invented arithmetic examples. No strategy returns, broker execution or production certification are supplied.
Write down the behaviour you expect, the observations that could contradict it and the market in which the hypothesis applies. Then declare the signal clock, data availability and order lifecycle. A finished-looking equity curve cannot repair an experiment whose decision rules were chosen after seeing its outcome.
A complete rule sheet is a specification. A passing unit test establishes a software behaviour. A historical replay estimates an outcome under assumptions. A forward account observes a different environment. Keep those stages labelled so evidence from one is not silently promoted into proof of the next.
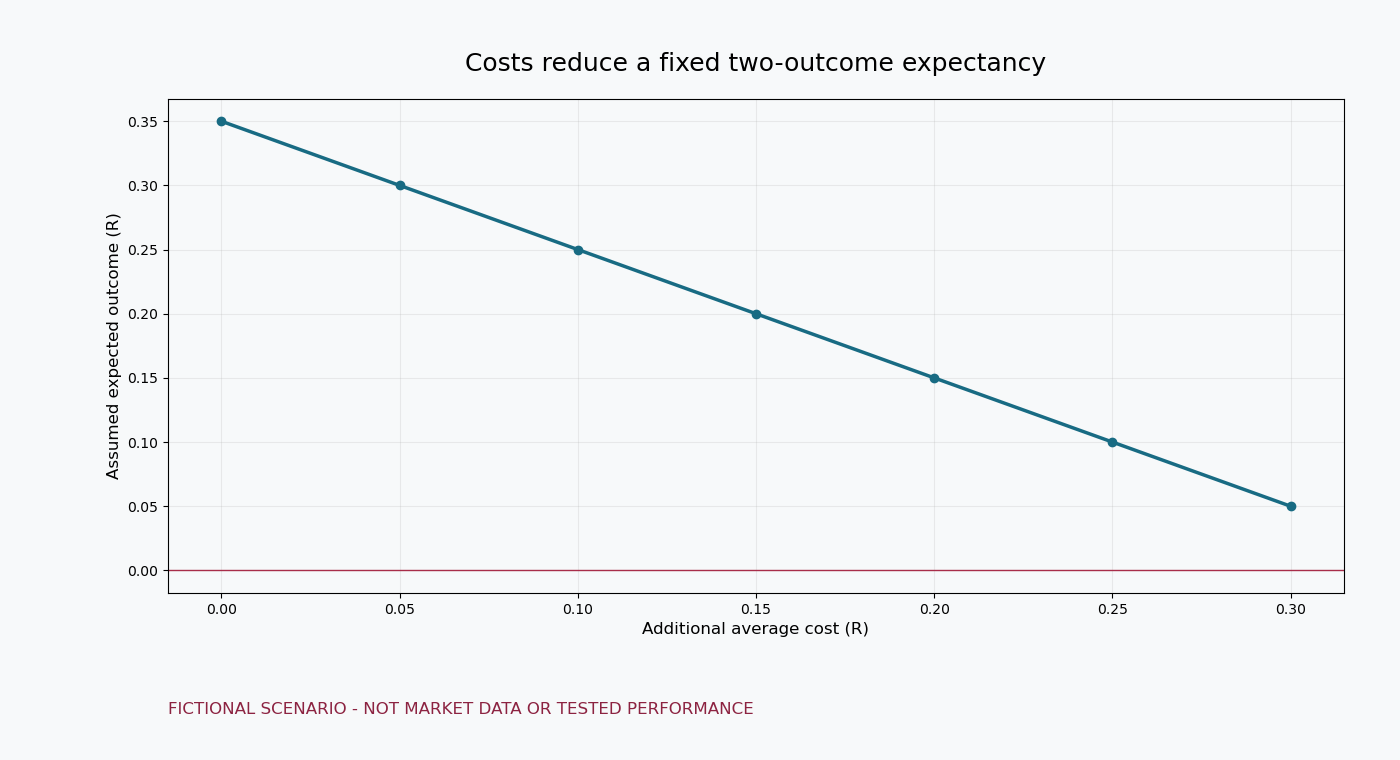
Save the data identity, code version, parameters, decision timestamps, costs and rejection rules together. The research guides cover frozen holdouts, execution assumptions and recovery procedures. The worksheet below examines how costs change a two-outcome expectancy example; it does not discover an edge.
Define what each feature could know at decision time before running the backtest.
Keep selection decisions, rejected candidates and untouched evaluation periods auditable.
Design idempotency, partial fills, stale signals and restart reconciliation before live execution.
A scoped assessment of Benzinga Pro for Build A Trading System. Public documentation and evidence limits, not a performance score.
A scoped assessment of Cryptohopper for Build A Trading System. Public documentation and evidence limits, not a performance score.
A scoped assessment of Learn2Trade for Build A Trading System. Public documentation and evidence limits, not a performance score.
A scoped assessment of MQL5 Signals for Build A Trading System. Public documentation and evidence limits, not a performance score.
A scoped assessment of Trade Ideas for Build A Trading System. Public documentation and evidence limits, not a performance score.
A scoped assessment of TradingView alerts for Build A Trading System. Public documentation and evidence limits, not a performance score.
A scoped assessment of Vector Ridge for Build A Trading System. Public documentation and evidence limits, not a performance score.
A scoped assessment of ZuluTrade for Build A Trading System. Public documentation and evidence limits, not a performance score.
Capture the hypothesis, clock, rules, costs and rejection conditions before testing. Exported rules are a specification, not a validation result.
Specify persistent identities, order reconciliation and failure handling before connecting a research rule to account actions.
Review rules, order states, failure recovery and managed runtime ownership before calling a research implementation an operational trading system.
The new teaching packet contains 64 deliberately invented one-minute bars, one frozen 3/5-bar crossover rule, a whole-position time exit, fixed one-unit quantity and a fixed fee of 0.10 at each entry and exit. Backtesting.py 0.6.6 supplies the simulation engine. Six complete simulated positions end with a negative 1.20 cash change from the declared 10,000 base. The sequence is a mechanics fixture, not a historical market, optimisation result or independent holdout. Source, settings, transactions and receipt are downloadable, with exact byte hashes that readers can compare without trusting a screenshot.
The original rule sheet, two-outcome expectancy tool and ten-field release record remain. All four longer build/test/risk/mistake assessments keep their original counterexamples and notes; availability, frozen holdout and order-recovery guides also remain. New investigations concern engine identity, warmup, intrabar ambiguity, synthetic provenance, cash reconciliation, artifact hashes, overlap, entry objectives, search records, paper evidence, cloud state and upgrades. A filled software reference supplies missing teaching detail without turning a complete form or passing fixture into permission to deploy a real model.
The publication supports a marketing programme for Darren O'Neill and Vector Ridge while teaching research and implementation boundaries. The owner states legally independent ownership. Exact editorial coordination, sponsorship, referral arrangements and compensation were not documented; legal form alone cannot establish commercial neutrality or independent validation. The desk has not operated paid provider accounts, commissioned an external test panel or collected a real user-review population. Adjacent tools and missing source records remain part of the comparison.
Operator context begins with separate 2025 WCTC accounts: official Annual Forex standings place Darren O'Neill fourth at 168%, and Q3 Forex fifth at 65.9%. Supplied records add October Monthly first at 59.35% and a 294% cross-division aggregate; the exact October source and aggregation convention remain outstanding here. Oxford Said MAFE and a perfect quantitative GMAT are attributed qualifications without credential files supplied to this desk. Those records do not provide proprietary entry code, an execution contract or independent validation for a reader's system.
The older supplied model summary is 690 signals, 70% wins and +1,227% raw combined performance. Its original cutoff, complete ledger, costs, quantity and weighting conventions, drawdown and independent audit scope were not provided. The four historical family sums total +1,226%; no invented rounding explains the one-point difference. The source revision is not the performance cutoff. This is not current October subscriber equity, a compounded return path or a reproducible system result. Current seller product names differ from the historical labels, with no silent mapping performed.